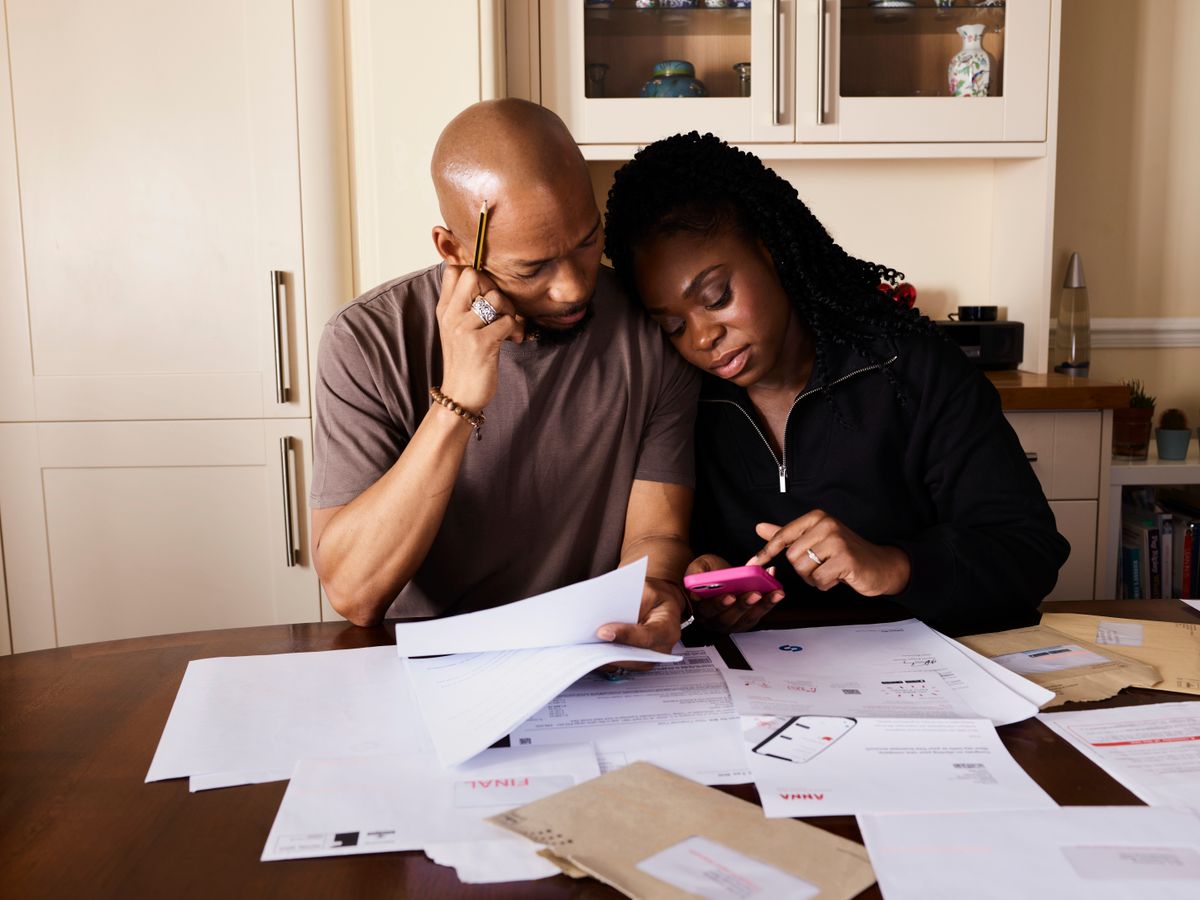
Check your agreement before changing your budget.
What happened
The Guardian reports that the Bank of England increased its base rate to 4%.
Its explanation distinguishes fixed mortgage agreements from tracker and standard variable arrangements.
Existing fixed mortgage payments remain unchanged until the current agreement ends, according to the report.
Tracker borrowing costs respond to the base rate under the relevant mortgage terms.
The article explains that standard variable rates depend on the lender's decision.
It also notes that savings providers may respond differently to the announcement.
This is a United Kingdom development involving its central bank and financial providers.
It does not announce a corresponding rate decision for every country.
Readers elsewhere should consult their own agreements and relevant provider notices.
The useful starting point is identifying which terms actually govern your savings or borrowing.
The background explained
A household budget connects regular income with essential spending and future commitments.
It helps distinguish obligations from purchases that can wait. That distinction supports clearer decisions when circumstances change.
Cash flow describes when money arrives and when payments leave. Timing matters even when total income appears sufficient.
An emergency reserve provides accessible money for unexpected expenses. Its purpose differs from money committed to longer plans.
Borrowing creates contractual obligations that continue until repayment or an agreed change. Always read the relevant agreement before assuming flexibility.
Savings accounts also carry conditions governing access, interest and withdrawals. A headline return cannot explain every condition.
Fixed terms and variable terms allocate uncertainty differently. Understanding that difference helps people compare suitable arrangements.
Financial resilience means having practical options when circumstances become difficult. It depends on commitments, accessible resources and individual needs.
These concepts apply across countries, although contracts and local protections differ. General explanations cannot replace the terms governing your own accounts.
Why it matters to you
Start by separating the reported event from your actual financial exposure.
A headline can feel urgent without changing your immediate contractual obligations. Your account documents provide the relevant starting point.
Write down essential expenses before considering optional spending changes. Include commitments that arrive less frequently than your usual bills.
Consider which payments depend on reliable income arriving on time. This reveals where a disruption would require attention first.
Keep money for near-term essentials accessible under terms you understand. Avoid assuming every savings product permits immediate withdrawals.
Compare the full cost of any proposed financial change. Fees and restrictions can matter alongside an advertised rate.
Check whether your information comes from an announcement or an individual notice. Those documents answer different questions about your circumstances.
If you share household finances, discuss responsibilities before changing arrangements. Clear communication helps prevent conflicting assumptions about available money.
Treat educational examples as prompts for checking your own documents. They cannot establish the payment required under your particular agreement.
A considered response begins with verified information and realistic priorities. It does not require predicting the next market movement.
Photo by Jakub Zerdzicki on Pexels.
Who is affected
Savers should check account access conditions and the purpose of their reserves. Separate everyday cash needs from money intended for longer commitments.
Borrowers should identify payment obligations and the terms governing any changes. Ask the provider to explain unclear language before making decisions.
Workers can review essential spending against the reliability of their income. Keep relevant employment documents and household payment records readily available.
Business owners can review operating commitments alongside incoming customer payments. Distinguish business cash needs from personal spending responsibilities.
People can belong to several groups at the same time. A worker may also borrow, save and operate a small business.
Consider these connections when reviewing your overall position. Solving an isolated problem can create difficulties elsewhere in the budget.
What to do now
- Read the original report and identify the confirmed development. Separate reported facts from commentary about possible outcomes.
- Collect your relevant account agreements and recent statements. Mark payment dates, access restrictions and any terms requiring clarification.
- Write an essential spending plan using your own records. Include household commitments before allocating money to optional purchases.
- Check accessible reserves against upcoming obligations. Consider the timing of payments alongside the timing of expected income.
- Contact the relevant provider with specific questions about your agreement. Request written explanations before accepting changes you do not understand.
- Review the plan with anyone sharing responsibility for these finances. Seek appropriate local guidance when contractual decisions require individual advice.
Key terms
- Cash flow: the timing of incoming and outgoing money.
- Fixed terms: conditions agreed for a specified period.
- Variable terms: conditions that may change under an agreement.
- Accessible reserves: money available for unexpected spending.
FAQ
Does this report change every household budget?
No automatic conclusion applies to every reader. Start with your actual exposure and the terms of your agreements.
Should I change financial products immediately?
Compare your needs, costs and restrictions before deciding. A news headline alone cannot establish which arrangement suits you.
What information should I keep?
Keep relevant statements, agreements and written provider explanations together. Use those records when checking obligations or requesting help.
Source: Original report.
 Article
 Article
 Article
 Article
 Article
 Article
 Article